Click Here for Townhall Dates/Times/Locations
FREQUENTLY ASKED QUESTIONS ABOUT THE PROPERTY TAX REDUCTION LOST (PTRLOST)
PTRLOST stands for Property Tax Relief Local Option Sales Tax. It is also known as the Floating Local Option Sales Tax, or FLOST. Both names refer to the same proposed countywide sales and use tax.
PTRLOST was authorized by Georgia House Bill 581 in 2024 to provide property tax relief by reducing the millage rates levied by counties and qualifying participating municipalities.
“FLOST” is the term used by the Georgia Department of Revenue, while “PTRLOST” more clearly communicates the tax’s purpose. Throughout this FAQ, PTRLOST and FLOST refer to the same proposed tax.
House Bill 581 also made other statewide changes involving property tax estimate notices, property tax appeals, sales-ratio studies, homestead exemptions and local sales-tax limits. Those provisions are separate from the proposed PTRLOST referendum.
PTRLOST stands for Property Tax Relief Local Option Sales Tax. It is also known as the Floating Local Option Sales Tax, or FLOST. Both names refer to the same proposed countywide sales and use tax. PTRLOST was authorized by Georgia House Bill 581 in 2024 to provide property tax relief by reducing the millage rates levied by counties and qualifying participating municipalities. “FLOST” is the term used by the Georgia Department of Revenue, while “PTRLOST” more clearly communicates the tax’s purpose. Throughout this FAQ, PTRLOST and FLOST refer to the same proposed tax. House Bill 581 also made other statewide changes involving property tax estimate notices, property tax appeals, sales-ratio studies, homestead exemptions and local sales-tax limits. Those provisions are separate from the proposed PTRLOST referendum.
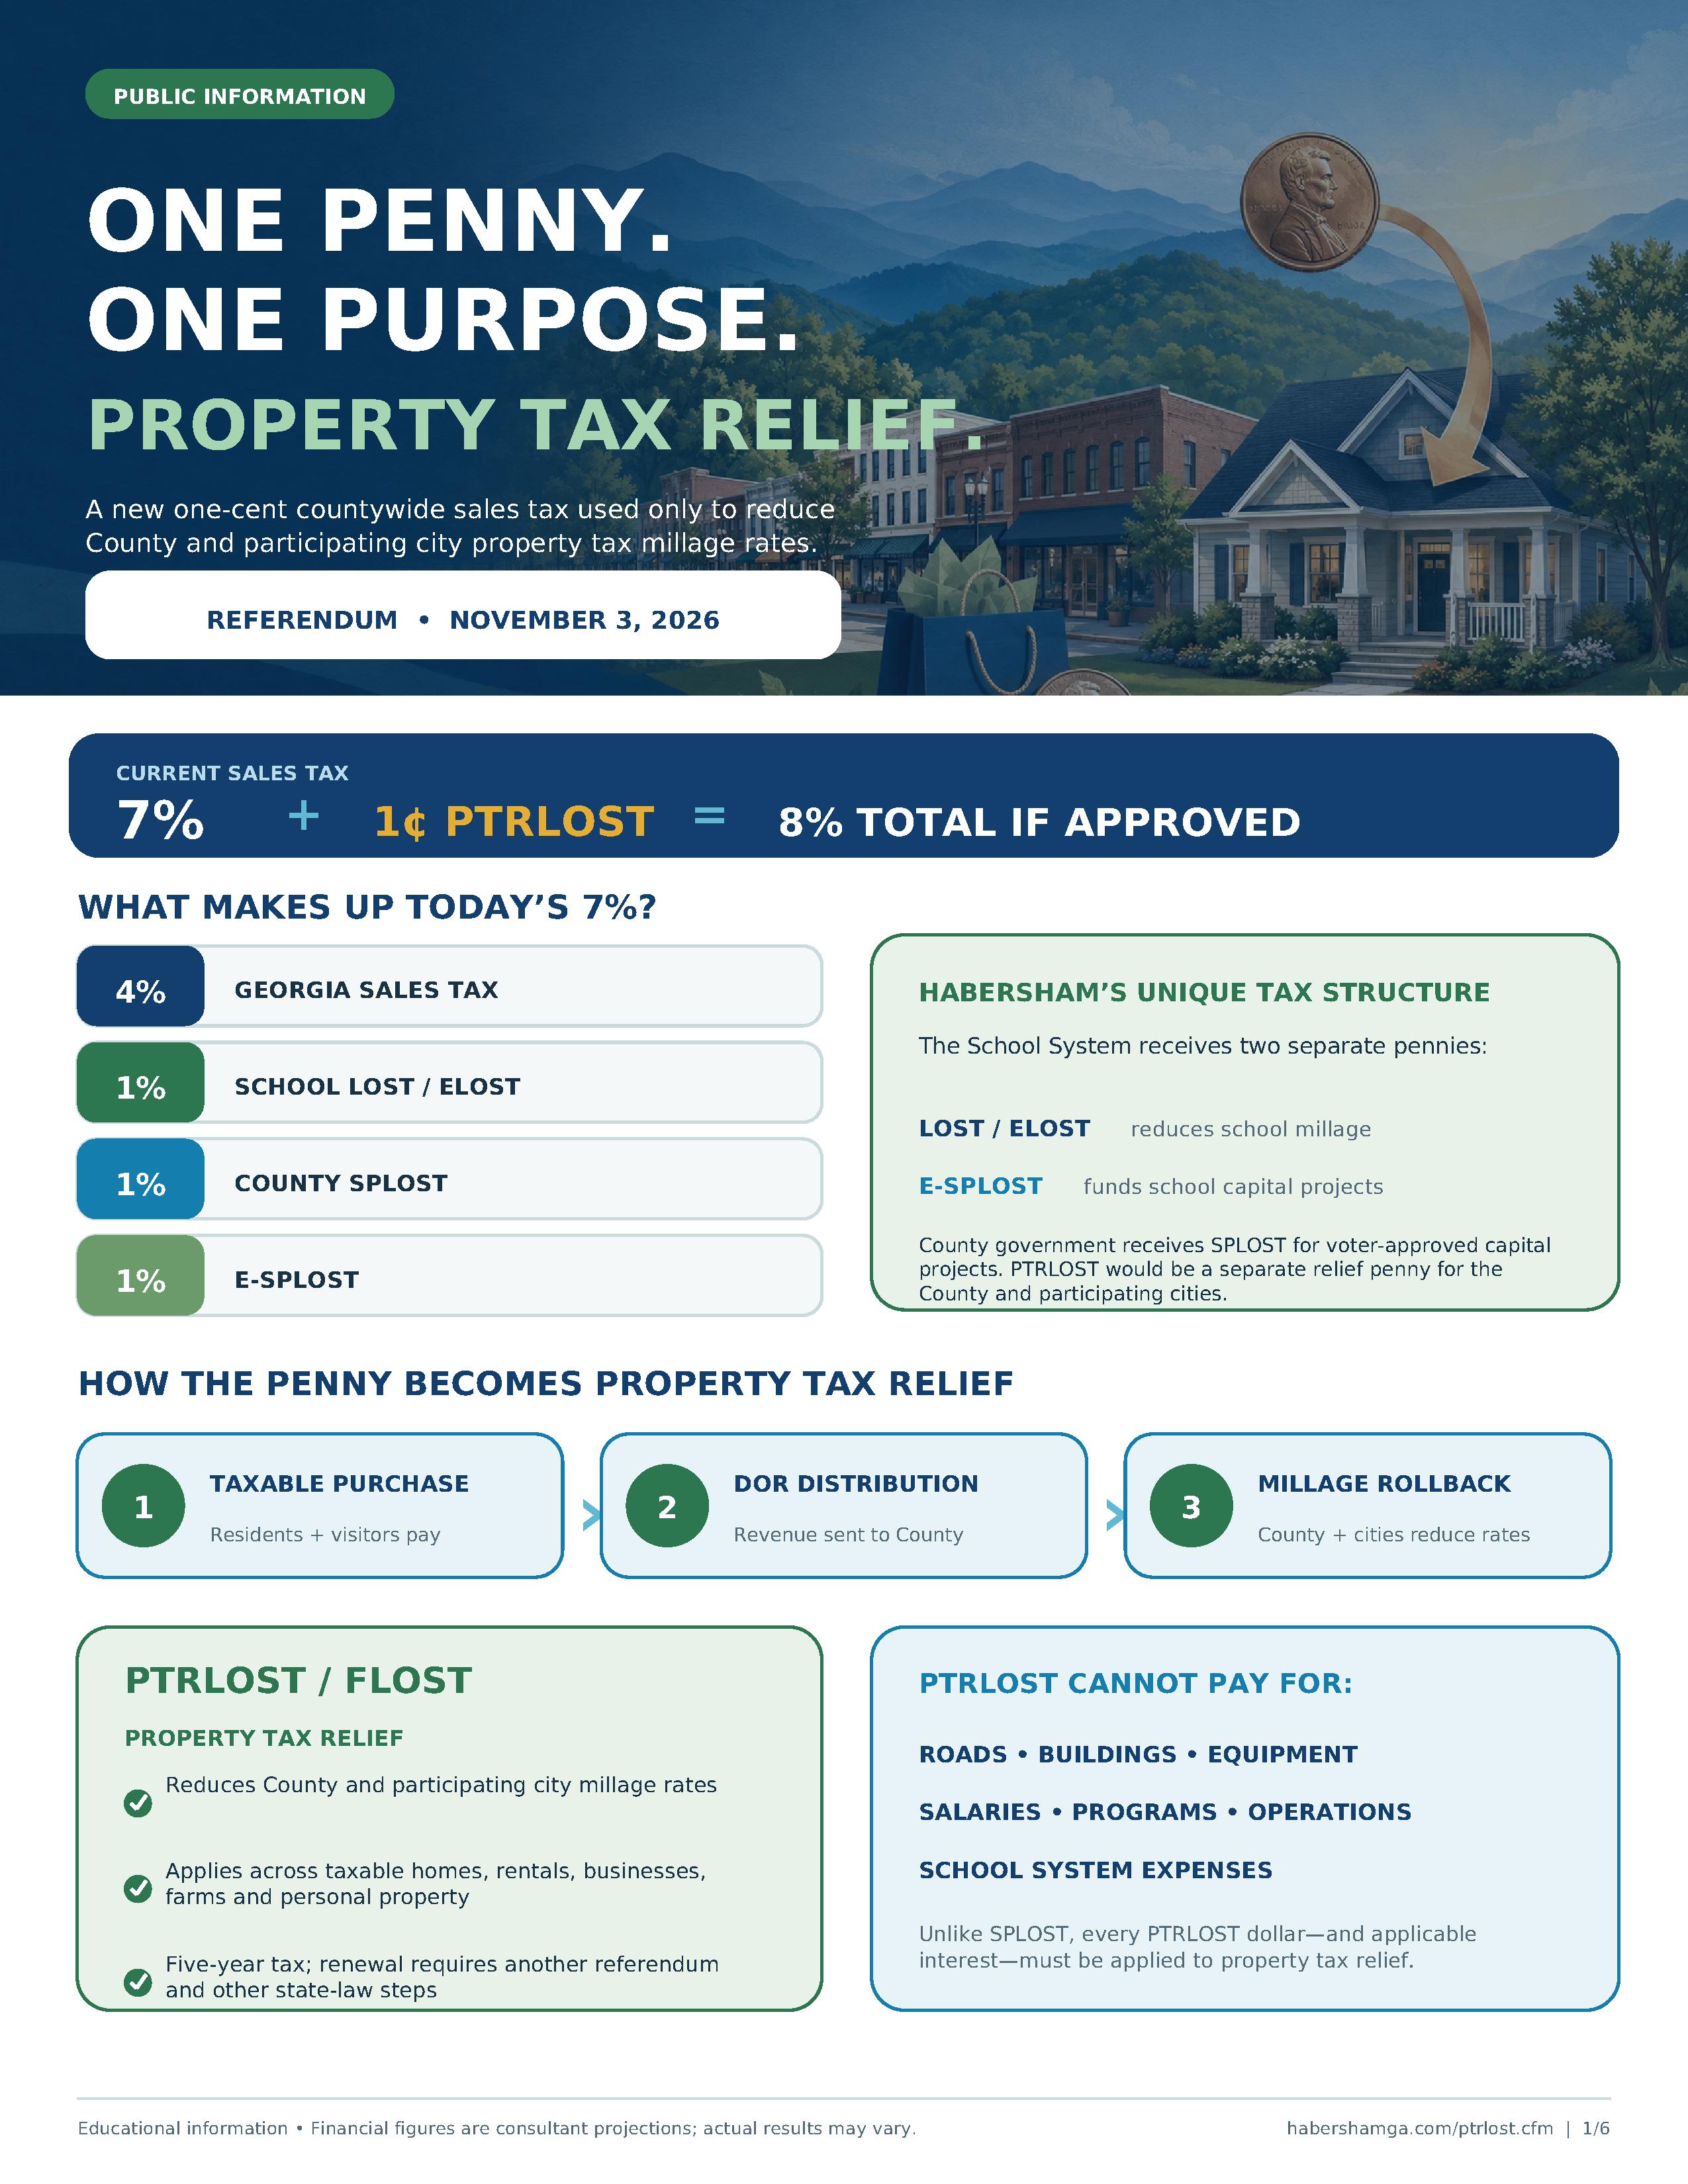
Yes. PTRLOST would be a new 1% sales tax, equal to one penny on each dollar spent on purchases subject to Georgia sales tax.
PTRLOST cannot be imposed without voter approval. Habersham County voters will decide whether to approve the tax in a countywide referendum on November 3, 2026.
If approved, Habersham County’s total sales tax rate would increase from 7% to 8%.
Yes. PTRLOST would be a new 1% sales tax, equal to one penny on each dollar spent on purchases subject to Georgia sales tax. PTRLOST cannot be imposed without voter approval. Habersham County voters will decide whether to approve the tax in a countywide referendum on November 3, 2026. If approved, Habersham County’s total sales tax rate would increase from 7% to 8%.
If approved, PTRLOST collections are scheduled to begin January 1, 2027. The tax would remain in effect for five years and expire December 31, 2031.
Calendar year 2027 would be the first full year of collections. Those collections would be applied during the 2028 property tax millage-rate-setting process. Therefore, 2028 would be the first property tax year in which taxpayers would receive the full projected millage-rate reduction.
PTRLOST would not continue automatically after five years. Renewal would require a local act of the Georgia General Assembly, compliance with the other requirements of state law and approval by voters in another referendum.
If approved, PTRLOST collections are scheduled to begin January 1, 2027. The tax would remain in effect for five years and expire December 31, 2031. Calendar year 2027 would be the first full year of collections. Those collections would be applied during the 2028 property tax millage-rate-setting process. Therefore, 2028 would be the first property tax year in which taxpayers would receive the full projected millage-rate reduction. PTRLOST would not continue automatically after five years. Renewal would require a local act of the Georgia General Assembly, compliance with the other requirements of state law and approval by voters in another referendum.
Habersham County’s current total sales tax rate is 7%.
| Tax | Rate | Purpose |
|---|---|---|
| Georgia state sales tax | 4% | State government purposes |
| LOST/ELOST | 1% | Received by the Habersham County School System and applied toward reducing the school property tax millage rate |
| E-SPLOST | 1% | Funds voter-approved educational capital projects |
| County SPLOST | 1% | Funds voter-approved County and municipal capital projects |
| Current total | 7% |
Habersham County government receives a portion of the current SPLOST VII. Voters have approved its renewal, and SPLOST VIII will succeed SPLOST VII when the current program ends.
If PTRLOST is approved, it would add another 1%, increasing the total sales tax rate to 8%.
The School System receives revenue from two separate one-cent sales taxes with different legally authorized purposes:
- LOST/ELOST is applied dollar-for-dollar toward reducing the School System’s property tax millage rate.
- E-SPLOST funds voter-approved educational capital investments, including school construction and renovations, technology, equipment and school buses.
Habersham County government did not voluntarily transfer or “give away” its LOST revenue to the School System.
In 1984, a special constitutional amendment authorized the School System to levy an Education Local Option Sales Tax for school property tax relief. A 1992 state law subsequently counted that tax against the statutory limit on local sales taxes. This prevented the County government from proposing a traditional county-and-municipal LOST under the laws then in effect.
The current arrangement resulted from state and constitutional law—not a voluntary decision by the Habersham County Board of Commissioners.
The School System receives revenue from two separate one-cent sales taxes with different legally authorized purposes: LOST/ELOST is applied dollar-for-dollar toward reducing the School System’s property tax millage rate. E-SPLOST funds voter-approved educational capital investments, including school construction and renovations, technology, equipment and school buses. Habersham County government did not voluntarily transfer or “give away” its LOST revenue to the School System. In 1984, a special constitutional amendment authorized the School System to levy an Education Local Option Sales Tax for school property tax relief. A 1992 state law subsequently counted that tax against the statutory limit on local sales taxes. This prevented the County government from proposing a traditional county-and-municipal LOST under the laws then in effect. The current arrangement resulted from state and constitutional law—not a voluntary decision by the Habersham County Board of Commissioners.
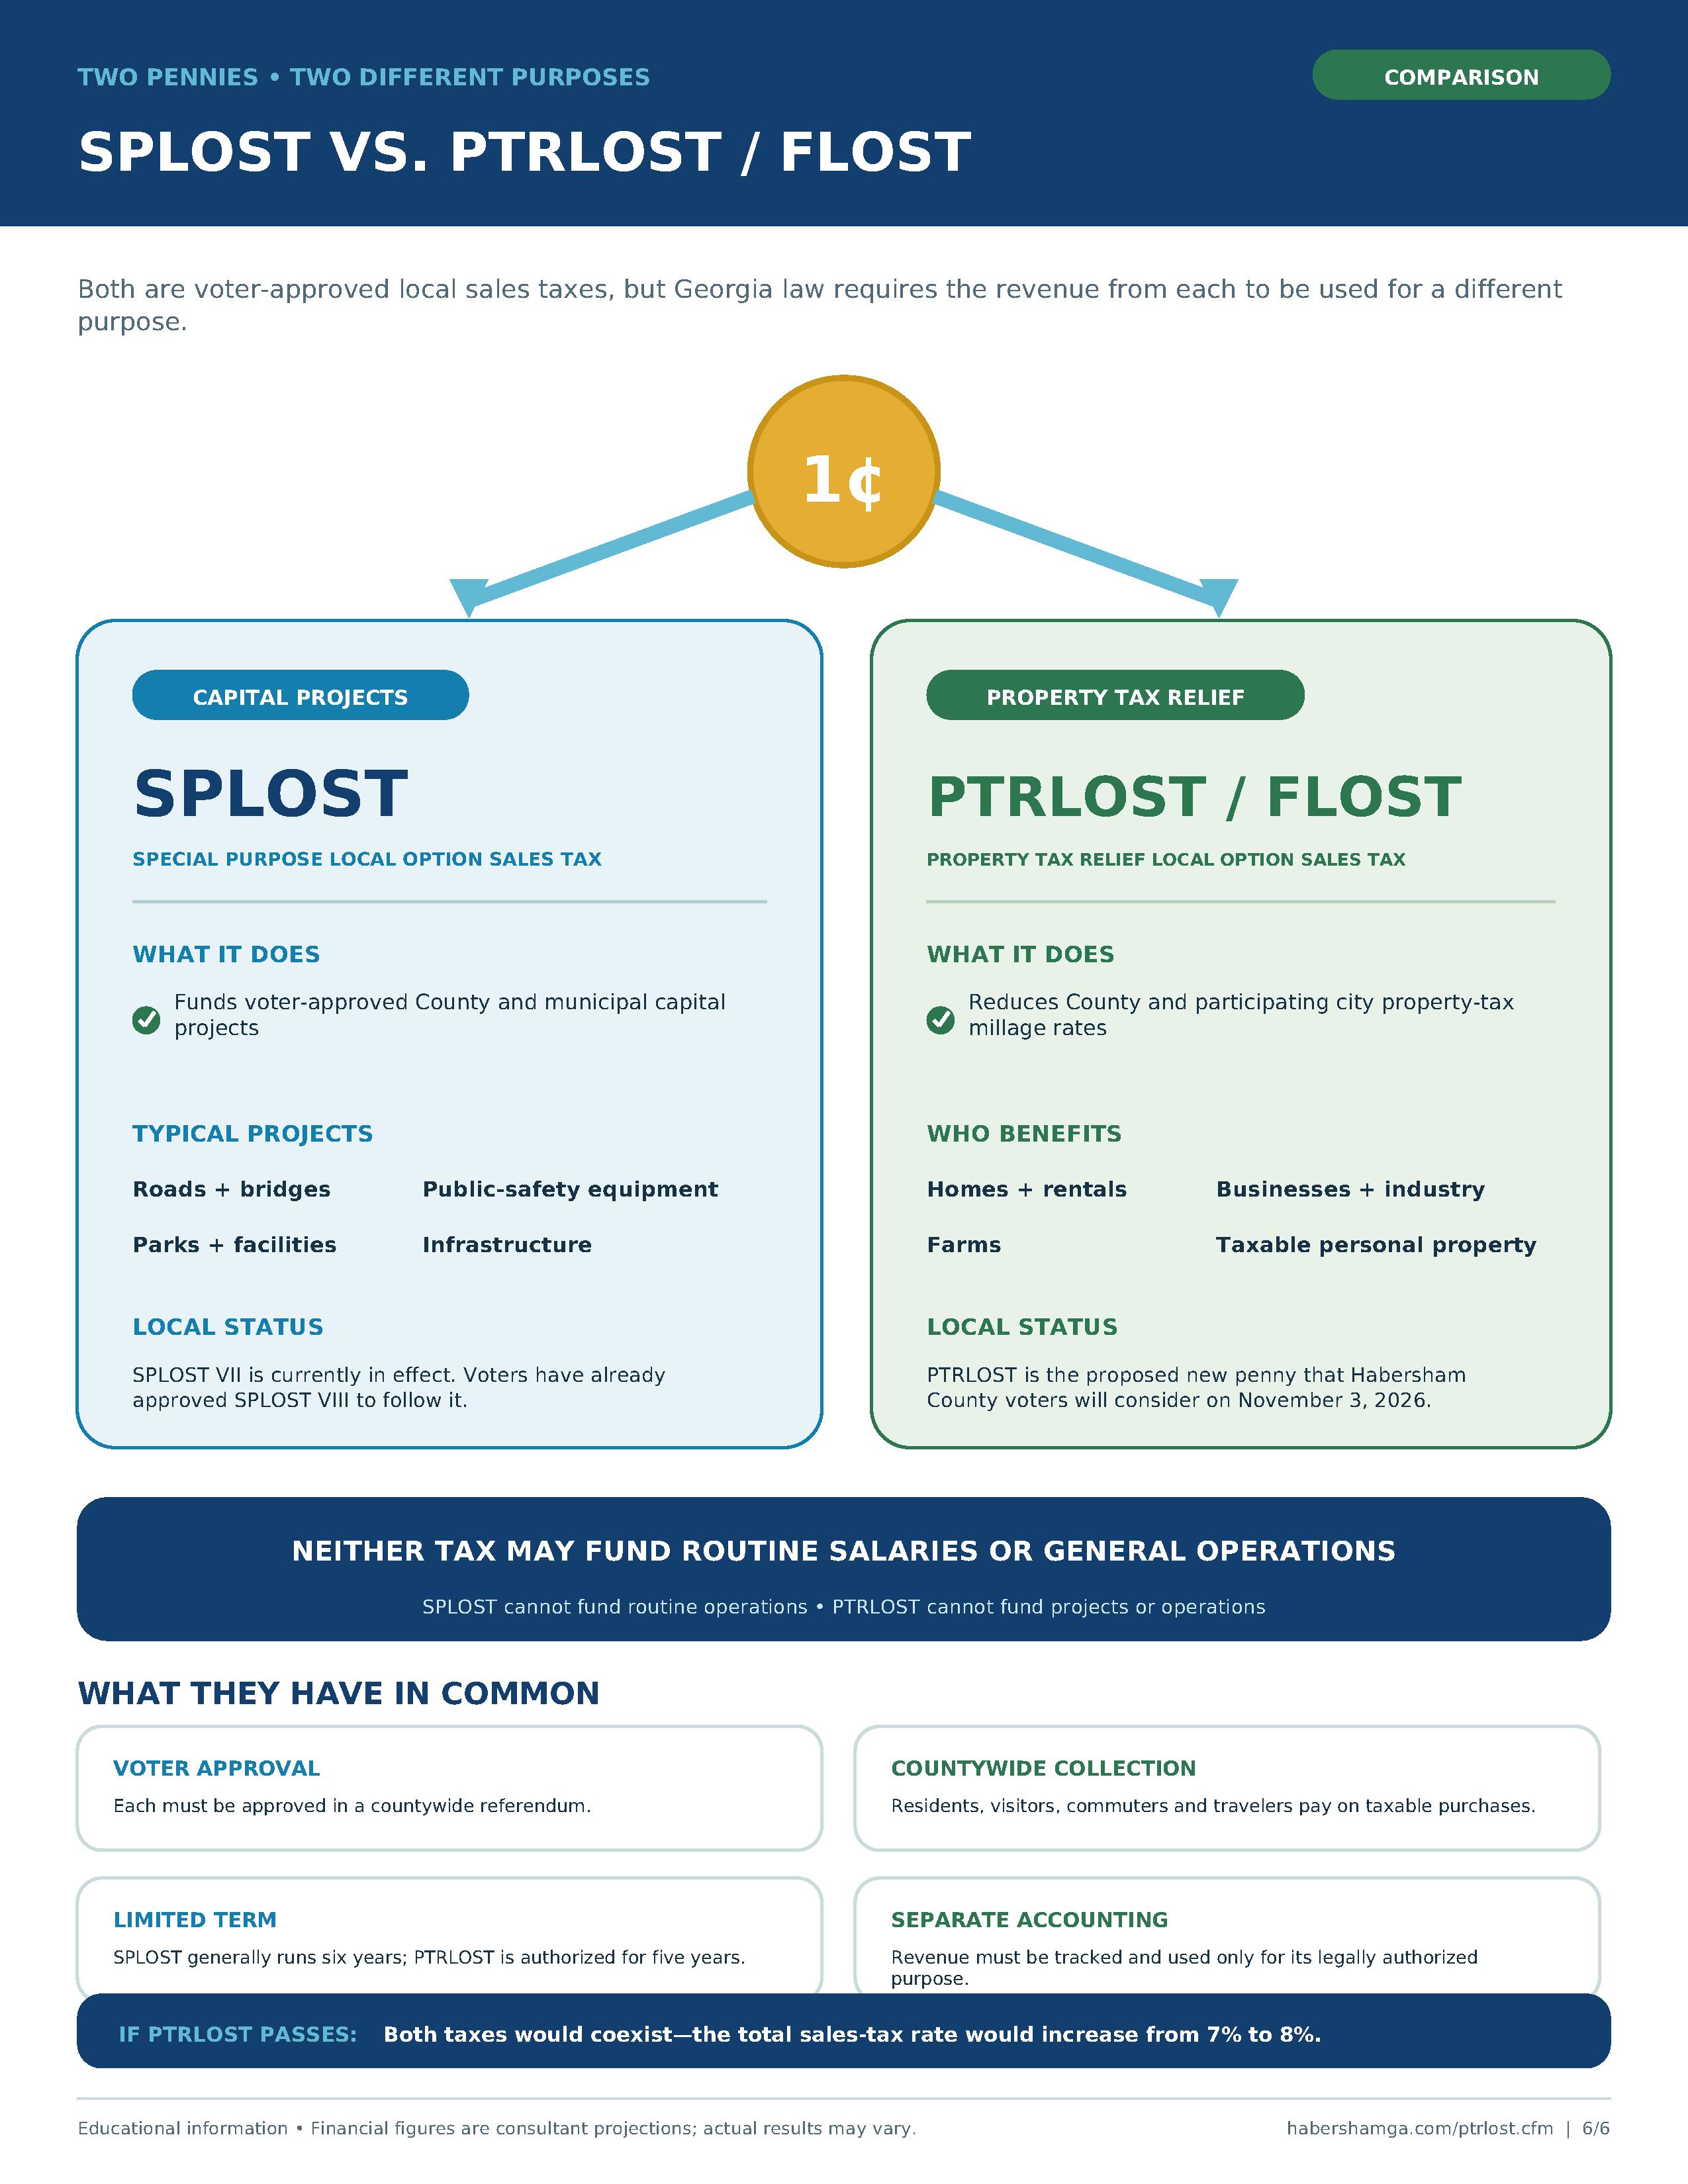
No. These are separate sales taxes with different legally authorized uses.
| Tax | Primary purpose |
|---|---|
| School LOST/ELOST | Reduces the School System’s property tax millage rate |
| E-SPLOST | Funds voter-approved educational capital projects |
| County SPLOST | Funds voter-approved County and municipal capital projects |
| PTRLOST/FLOST | Reduces County and participating municipal property tax millage rates |
PTRLOST would not replace LOST/ELOST, E-SPLOST, SPLOST VII or the voter-approved SPLOST VIII.
Habersham County would continue using SPLOST revenue for voter-approved capital projects while separately applying PTRLOST revenue toward property tax relief.
No. These are separate sales taxes with different legally authorized uses. Tax Primary purpose School LOST/ELOST Reduces the School System’s property tax millage rate E-SPLOST Funds voter-approved educational capital projects County SPLOST Funds voter-approved County and municipal capital projects PTRLOST/FLOST Reduces County and participating municipal property tax millage rates PTRLOST would not replace LOST/ELOST, E-SPLOST, SPLOST VII or the voter-approved SPLOST VIII. Habersham County would continue using SPLOST revenue for voter-approved capital projects while separately applying PTRLOST revenue toward property tax relief.
PTRLOST revenue must be used exclusively to reduce the property tax millage rates of Habersham County and qualifying participating municipalities.
PTRLOST revenue cannot be used for:
- Roads, buildings or other capital projects
- Equipment or vehicle purchases
- New programs
- Employee salaries or benefits
- General government operations
- School System expenses
- Other discretionary expenditures
Likewise, SPLOST revenue cannot be substituted for the property tax relief legally required under PTRLOST.
PTRLOST revenue must be used exclusively to reduce the property tax millage rates of Habersham County and qualifying participating municipalities. PTRLOST revenue cannot be used for: Roads, buildings or other capital projects Equipment or vehicle purchases New programs Employee salaries or benefits General government operations School System expenses Other discretionary expenditures Likewise, SPLOST revenue cannot be substituted for the property tax relief legally required under PTRLOST.
PTRLOST revenue would replace a portion of the revenue that Habersham County and participating municipalities would otherwise need to collect from property owners.
Each government’s PTRLOST proceeds would be converted into an equivalent number of property tax mills. That millage equivalent would then be used to reduce the government’s property tax millage rate.
PTRLOST would not provide individual rebate or refund checks. The benefit would be delivered through a lower millage rate than would otherwise be required.
PTRLOST revenue would replace a portion of the revenue that Habersham County and participating municipalities would otherwise need to collect from property owners. Each government’s PTRLOST proceeds would be converted into an equivalent number of property tax mills. That millage equivalent would then be used to reduce the government’s property tax millage rate. PTRLOST would not provide individual rebate or refund checks. The benefit would be delivered through a lower millage rate than would otherwise be required.
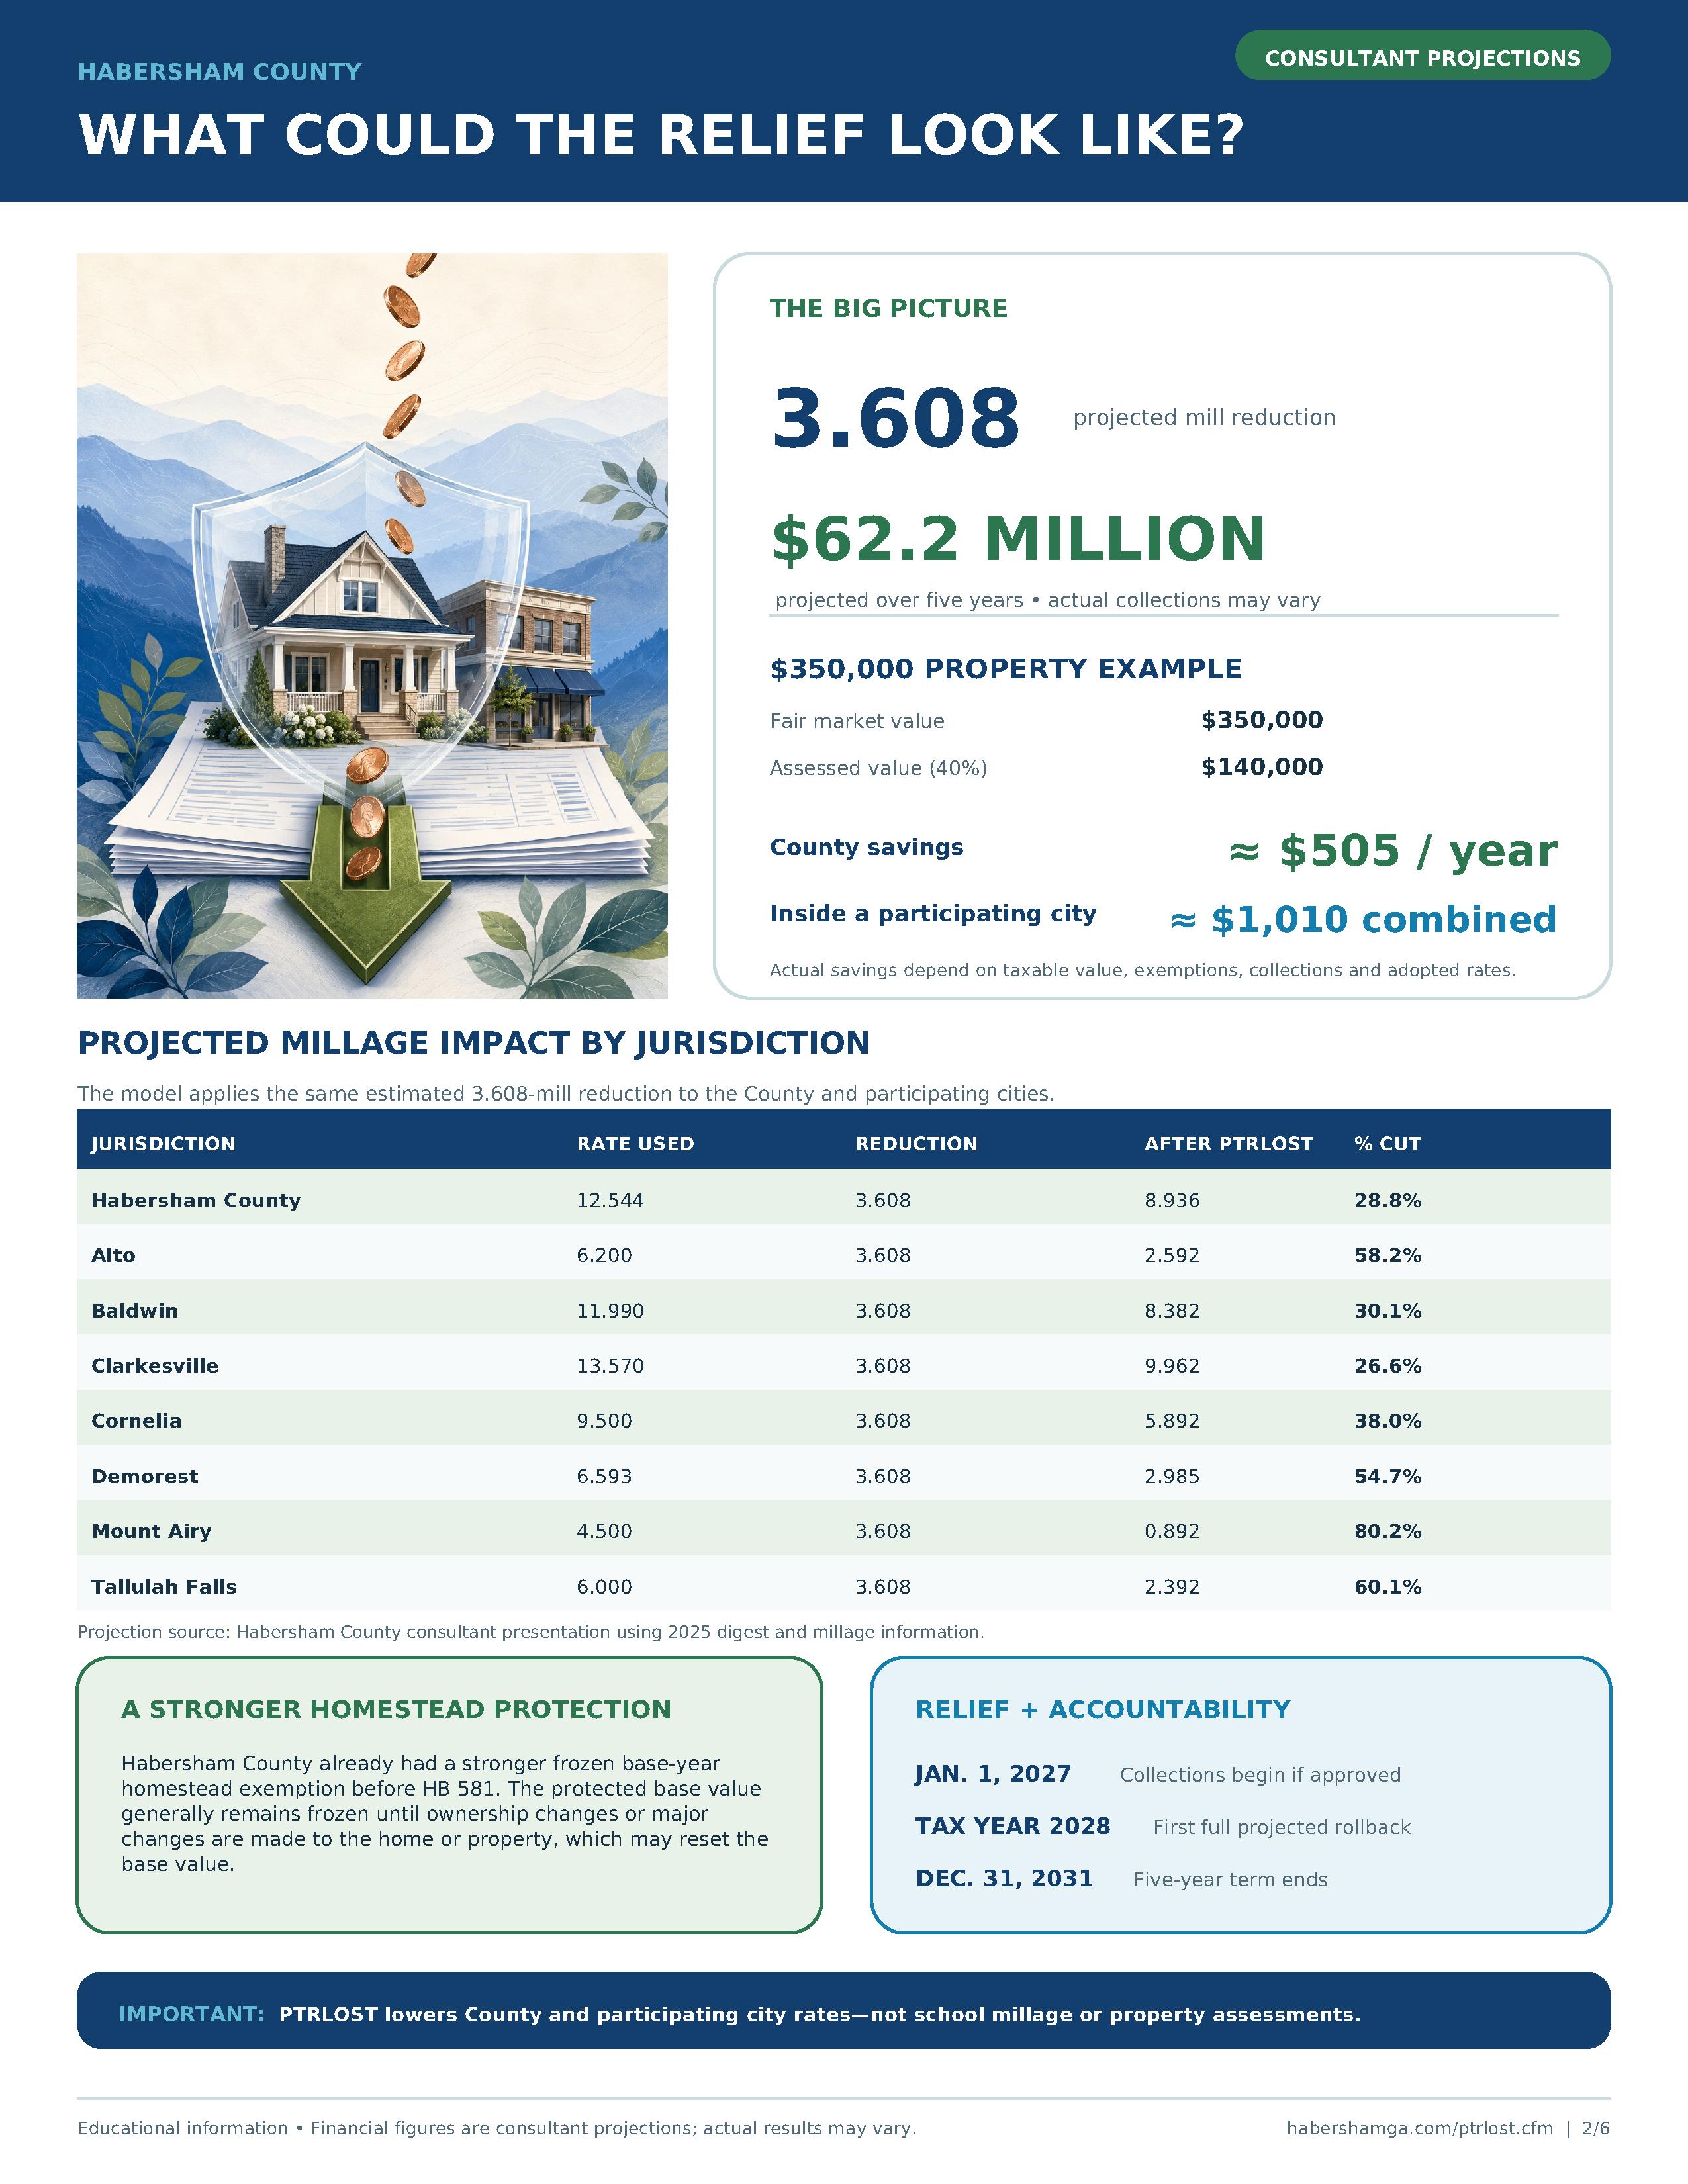
The Habersham-specific consultant analysis projects that PTRLOST could generate approximately $62,239,530 over the five-year period.
The initial millage-reduction model uses approximately $10,619,052 in projected annual revenue for Habersham County and the participating municipalities.
These figures are projections, not guaranteed collections. Actual revenue may be higher or lower depending on taxable sales activity in Habersham County.
The Habersham-specific consultant analysis projects that PTRLOST could generate approximately $62,239,530 over the five-year period. The initial millage-reduction model uses approximately $10,619,052 in projected annual revenue for Habersham County and the participating municipalities. These figures are projections, not guaranteed collections. Actual revenue may be higher or lower depending on taxable sales activity in Habersham County.
An intergovernmental agreement establishes how the proceeds will be divided between Habersham County and qualifying participating municipalities.
The consultant’s model divides the projected revenue based on property tax digests and the amount necessary to provide the same estimated 3.608-mill reduction to the County and each participating municipality.
| Jurisdiction | Projected revenue | Projected share |
|---|---|---|
| Habersham County | $7,811,194 | 73.56% |
| Alto | $57,666 | 0.54% |
| Baldwin | $462,960 | 4.36% |
| Clarkesville | $507,215 | 4.78% |
| Cornelia | $1,223,056 | 11.52% |
| Demorest | $264,056 | 2.49% |
| Mount Airy | $203,371 | 1.92% |
| Tallulah Falls | $89,534 | 0.84% |
| Projected total | $10,619,052 | 100% |
These figures are estimates based on the tax digests, millage rates and revenue assumptions used in the consultant’s analysis. Actual distributions will depend on collections, updated tax-digest values and the governing intergovernmental agreement.
An intergovernmental agreement establishes how the proceeds will be divided between Habersham County and qualifying participating municipalities. The consultant’s model divides the projected revenue based on property tax digests and the amount necessary to provide the same estimated 3.608-mill reduction to the County and each participating municipality. Jurisdiction Projected revenue Projected share Habersham County $7,811,194 73.56% Alto $57,666 0.54% Baldwin $462,960 4.36% Clarkesville $507,215 4.78% Cornelia $1,223,056 11.52% Demorest $264,056 2.49% Mount Airy $203,371 1.92% Tallulah Falls $89,534 0.84% Projected total $10,619,052 100% These figures are estimates based on the tax digests, millage rates and revenue assumptions used in the consultant’s analysis. Actual distributions will depend on collections, updated tax-digest values and the governing intergovernmental agreement.
The consultant provided an example using property with:
- A fair market value of $350,000
- A 40% assessed value of $140,000
- A projected millage reduction of 3.608 mills
The estimated County property tax savings would be:
$140,000×0.003608=$505.12
The projected annual savings on the County portion of the tax bill would therefore be approximately $505.
The actual savings for a particular property will depend on its taxable value, exemptions, actual PTRLOST collections and the millage rate that would otherwise be required.
The consultant provided an example using property with: A fair market value of $350,000 A 40% assessed value of $140,000 A projected millage reduction of 3.608 mills The estimated County property tax savings would be: $140,000×0.003608=$505.12 The projected annual savings on the County portion of the tax bill would therefore be approximately $505. The actual savings for a particular property will depend on its taxable value, exemptions, actual PTRLOST collections and the millage rate that would otherwise be required.
Yes. Property inside a participating municipality would benefit from both the County millage reduction and the applicable municipal millage reduction.
Using the consultant’s $350,000 property example, the projected savings would be:
- Approximately $505 on County property taxes
- Approximately $505 on municipal property taxes
- Approximately $1,010 in combined annual savings
Property in unincorporated Habersham County would receive the County reduction but does not have a municipal property tax levy to reduce.
The dollar reduction is the same in the example because the consultant’s model applies the same projected 3.608-mill reduction to the County and each participating municipality.
Yes. Property inside a participating municipality would benefit from both the County millage reduction and the applicable municipal millage reduction. Using the consultant’s $350,000 property example, the projected savings would be: Approximately $505 on County property taxes Approximately $505 on municipal property taxes Approximately $1,010 in combined annual savings Property in unincorporated Habersham County would receive the County reduction but does not have a municipal property tax levy to reduce. The dollar reduction is the same in the example because the consultant’s model applies the same projected 3.608-mill reduction to the County and each participating municipality.
PTRLOST provides an across-the-board millage-rate reduction. It is not limited to homeowners or properties receiving a homestead exemption.
The reduction can benefit taxable:
Owner-occupied homes
Rental properties
Commercial properties
Industrial properties
Agricultural properties
Other real and personal property
The exact dollar benefit will depend on the property’s taxable value, applicable exemptions, actual PTRLOST collections and the millage rates adopted for that year.
PTRLOST provides an across-the-board millage-rate reduction. It is not limited to homeowners or properties receiving a homestead exemption. The reduction can benefit taxable: Owner-occupied homes Rental properties Commercial properties Industrial properties Agricultural properties Other real and personal property The exact dollar benefit will depend on the property’s taxable value, applicable exemptions, actual PTRLOST collections and the millage rates adopted for that year.
No. PTRLOST would reduce the millage rates levied by Habersham County and participating municipalities. It would not reduce the Habersham County Board of Education’s millage rate.
PTRLOST would not replace existing state or local homestead exemptions. Qualifying property owners would continue to receive their applicable exemptions in addition to the benefit of a lower County or municipal millage rate.
PTRLOST also would not determine, freeze or reduce a property’s fair market or assessed value. Property values would continue to be established by the Habersham County Board of Tax Assessors in accordance with Georgia law.
No. PTRLOST would reduce the millage rates levied by Habersham County and participating municipalities. It would not reduce the Habersham County Board of Education’s millage rate. PTRLOST would not replace existing state or local homestead exemptions. Qualifying property owners would continue to receive their applicable exemptions in addition to the benefit of a lower County or municipal millage rate. PTRLOST also would not determine, freeze or reduce a property’s fair market or assessed value. Property values would continue to be established by the Habersham County Board of Tax Assessors in accordance with Georgia law.
Yes. Before HB 581 was enacted, Habersham County already had a local base-year, or “frozen,” homestead exemption that provides stronger protection than the statewide floating exemption established by HB 581.
Under Habersham County’s existing exemption, the taxable value of a qualifying homestead is generally frozen at its established base-year amount. The base value remains frozen until:
- The property changes ownership; or
- Major changes, additions or improvements are made to the home or property.
When ownership changes or major changes are made to the home or property, the base value may be reset to reflect the property’s updated value. Once the new base value is established, that amount becomes the new value protected by the County’s frozen homestead exemption.
By comparison, the HB 581 statewide floating exemption allows the taxable value of a qualifying homestead to increase annually based on the inflation rate established by the State Revenue Commissioner.
| Habersham County’s existing exemption | HB 581 statewide exemption |
|---|---|
| Generally freezes taxable value at the established base-year amount | Allows taxable value to increase annually with inflation |
| Base value remains frozen until ownership changes or major changes are made to the property | Adjusted base value may increase each year even when ownership does not change |
| A change in ownership or major property change may establish a new base value | A sale or substantial property change may also establish a new base value |
| Provides stronger protection against assessment-related tax increases | Limits annual increases but does not completely freeze taxable value |
Because Habersham County already had a more protective homestead exemption, the County did not need to replace it with the less-protective statewide exemption.
Participating municipalities use the applicable HB 581 adjusted base-year, or floating, homestead exemption. Under that exemption, taxable homestead value may increase annually by the applicable inflation rate and may also be reset following a sale or substantial renovation.
These homestead exemptions are separate from PTRLOST. The homestead exemption protects a qualifying primary residence against increases in taxable value, while PTRLOST reduces the millage rate applied to taxable property generally—including residential, rental, commercial, industrial and agricultural property.
PTRLOST guarantees that the revenue received will be applied toward reducing the applicable County and municipal millage rates. However, it does not guarantee that every total property tax bill will be lower than the previous year.
An individual tax bill may also be affected by:
- Changes in assessed value
- New construction or improvements
- Changes in exemptions
- School property taxes
- Municipal property taxes
- Bond millage
- Other applicable tax districts
The appropriate comparison is what the County or municipal portion of the tax bill would have been without the PTRLOST-funded reduction—not necessarily whether the total bill is lower than the previous year.
PTRLOST guarantees that the revenue received will be applied toward reducing the applicable County and municipal millage rates. However, it does not guarantee that every total property tax bill will be lower than the previous year. An individual tax bill may also be affected by: Changes in assessed value New construction or improvements Changes in exemptions School property taxes Municipal property taxes Bond millage Other applicable tax districts The appropriate comparison is what the County or municipal portion of the tax bill would have been without the PTRLOST-funded reduction—not necessarily whether the total bill is lower than the previous year.
PTRLOST would be paid by anyone who makes a taxable purchase in Habersham County. This includes residents, visitors and people who live outside the county but shop, dine, stay or conduct business here.
It would generally apply to purchases already subject to Georgia state and local sales and use taxes. PTRLOST would not independently change which products or transactions are taxable or exempt.
Retailers would collect the tax at the time of purchase and remit it to the Georgia Department of Revenue, generally by the 20th day of the following month. The Department would then distribute the applicable revenue to Habersham County, typically near the end of the month.
The Georgia Department of Revenue would distribute PTRLOST revenue to Habersham County. The County would retain its share and distribute the applicable shares to participating municipalities according to the intergovernmental agreement.
Each participating government must use its proceeds exclusively for property tax relief. PTRLOST funds are to be maintained in interest-bearing accounts, and interest earned while a government holds the funds becomes part of the amount available for property tax relief.
PTRLOST cannot reduce a millage rate below 0.000 mills. If collections exceed the amount needed to reduce a jurisdiction’s millage rate to zero, the excess must be carried forward and applied toward property tax relief in a subsequent year.
If collections are not enough to eliminate the millage rate, all available revenue would still be applied toward reducing it.
Habersham County and participating municipalities must account for all PTRLOST revenue and document how it is applied.
Required reporting includes:
- Distributions received from the Georgia Department of Revenue
- Revenue retained by the County
- Revenue distributed to participating municipalities
- Interest earned
- Allowable bank fees or charges
- Millage-rate reductions provided
- Revenue applied to property tax relief
- Any excess proceeds carried forward
The Georgia Department of Revenue uses several forms for this process:
- PT-32.1: Calculates the rollback millage rate and PTRLOST-funded reduction.
- PT-35: Certifies County millage rates.
- PT-38: Certifies municipal millage rates.
- PT-109C: Accounts for County PTRLOST revenue, distributions, interest and tax relief.
- PT-109M: Accounts for municipal PTRLOST revenue, interest and tax relief.
These reporting and certification requirements are intended to ensure that PTRLOST revenue is fully accounted for and used exclusively for property tax relief.